Ray’s Apartments
$1,300–$1,450 / mo
2- and 3-bedroom apartments in an established community on South Main.
Explore Ray’s →
Rent when flexibility and low upfront cash matter most. Buy when you’re ready for long-term control, more space and the costs that come with ownership. This guide compares both with real Nephi numbers: apartments from $1,300 a month and a Loveless Estates townhome example at $389,900.
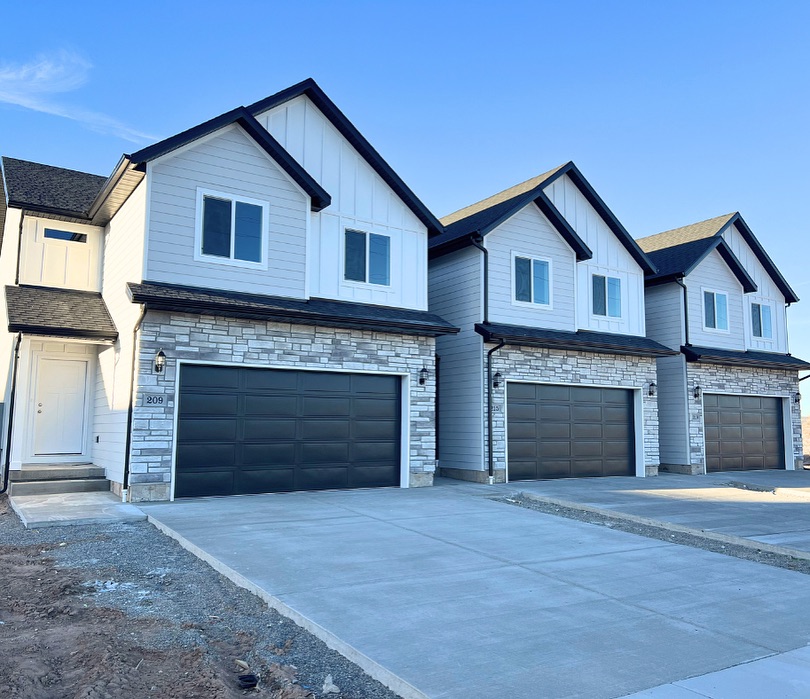
Neither path always wins. A good apartment can beat a rushed purchase, and a sound purchase can beat renting forever. Start with the list that sounds more like you.
Don’t buy just because “rent is throwing money away.” Rent buys housing, repairs handled by someone else, and flexibility. And don’t rent forever just because buying feels complicated. Compare what each path gives you for the time you’ll actually use it.
In this guide, the townhome is bought and owned; the apartment is rented under a lease. That legal relationship matters more than the building type.
| Factor | Townhome owner | Apartment renter |
|---|---|---|
| Your position | Owns the property, as defined by title and HOA documents | Has the right to live there under the lease |
| Upfront | Down payment, closing costs, inspection, moving and reserves | Deposit, first month’s rent, any pet charges, moving |
| Monthly | Mortgage, taxes, insurance, HOA, utilities, upkeep | Rent, renter’s insurance, utilities, any pet rent |
| Repairs | Owner handles the interior and anything not covered by the HOA | Management handles landlord repairs; renter handles tenant duties |
| Control | More freedom, within HOA rules and the law | Changes, pets and use limited by the lease |
| Leaving | Sell, keep or rent it out; timing and value uncertain | Usually leave at lease end after giving notice |
| Money outcome | May gain or lose equity | No equity, but keeps cash that would have gone into a purchase |
Use real local homes to compare, but confirm each one is still available at the price shown.
$1,300–$1,450 / mo
2- and 3-bedroom apartments in an established community on South Main.
Explore Ray’s →$1,550–$2,200 / mo
Newer 2-, 3- and 4-bedroom apartments beside Loveless Estates.
Explore Loveless →$389,900 example
233 W 815 N #53: 3 bedrooms, about 2,579 total sq ft, attached garage, fenced yard. Shown at this price on July 17, 2026.
Explore Loveless Estates →Compare finished space to finished space. The #53 listing reports about 2,579 total square feet, which includes unfinished basement area. Loveless Estates homes are commonly described at about 1,800 finished square feet plus basement potential. Apartment size varies by unit.
A renter needs the move-in amounts in the lease. A buyer needs a down payment plus costs that never become equity: lender and title charges, appraisal, inspection, prepaid taxes and insurance, moving, and savings left over after closing.
Program eligibility and mortgage insurance apply.
Plus closing costs, prepaid items and reserves.
Plus closing costs, inspection and reserves.
Typically avoids mortgage insurance; closing costs still apply.
| Upfront item | Buying a townhome | Renting an apartment |
|---|---|---|
| Main payment | Down payment chosen with your lender | First month’s or prorated rent |
| Transaction costs | Loan, appraisal, title, settlement, recording and inspection | Application or screening fees where charged |
| Deposits | Earnest money (usually credited at closing) | Security deposit ($750 at Priority Homes) and any pet deposit |
| Setting up | Furniture, blinds, tools and any appliances not included | Furniture and household items |
| Cash left over | Reserves for repairs, deductibles and HOA surprises | An emergency fund for moving and life changes |
Down-payment amounts are simple math on the $389,900 example, not loan offers. Eligibility, rates, mortgage insurance and closing costs depend on you, the property and the lender.
Mortgage principal and interest against rent isn’t a fair comparison. Add property tax, insurance, HOA dues, mortgage insurance and a repair reserve to the ownership side, and renter’s insurance and utilities to both.
Use a written lender quote and the current HOA statement for real numbers. The calculator is an estimate; nothing you type is saved or sent.
Equity comes from paying down the loan and from changes in market value. Neither is a guaranteed discount off today’s housing cost.
Each scheduled payment usually reduces the balance. How much depends on the loan amount, rate and term.
Values can rise, stay flat or fall. Treat any forecast as one scenario, not money already earned.
Mortgage-interest deductions depend on the law, limits and whether you itemize. See IRS Publication 936 and ask a tax adviser.
Run three exit dates: an earlier-than-planned sale (job or family change, flat value, full selling costs), your expected sale, and a long hold. A short or uncertain stay often favors renting, because buying and selling costs have less time to be spread out.
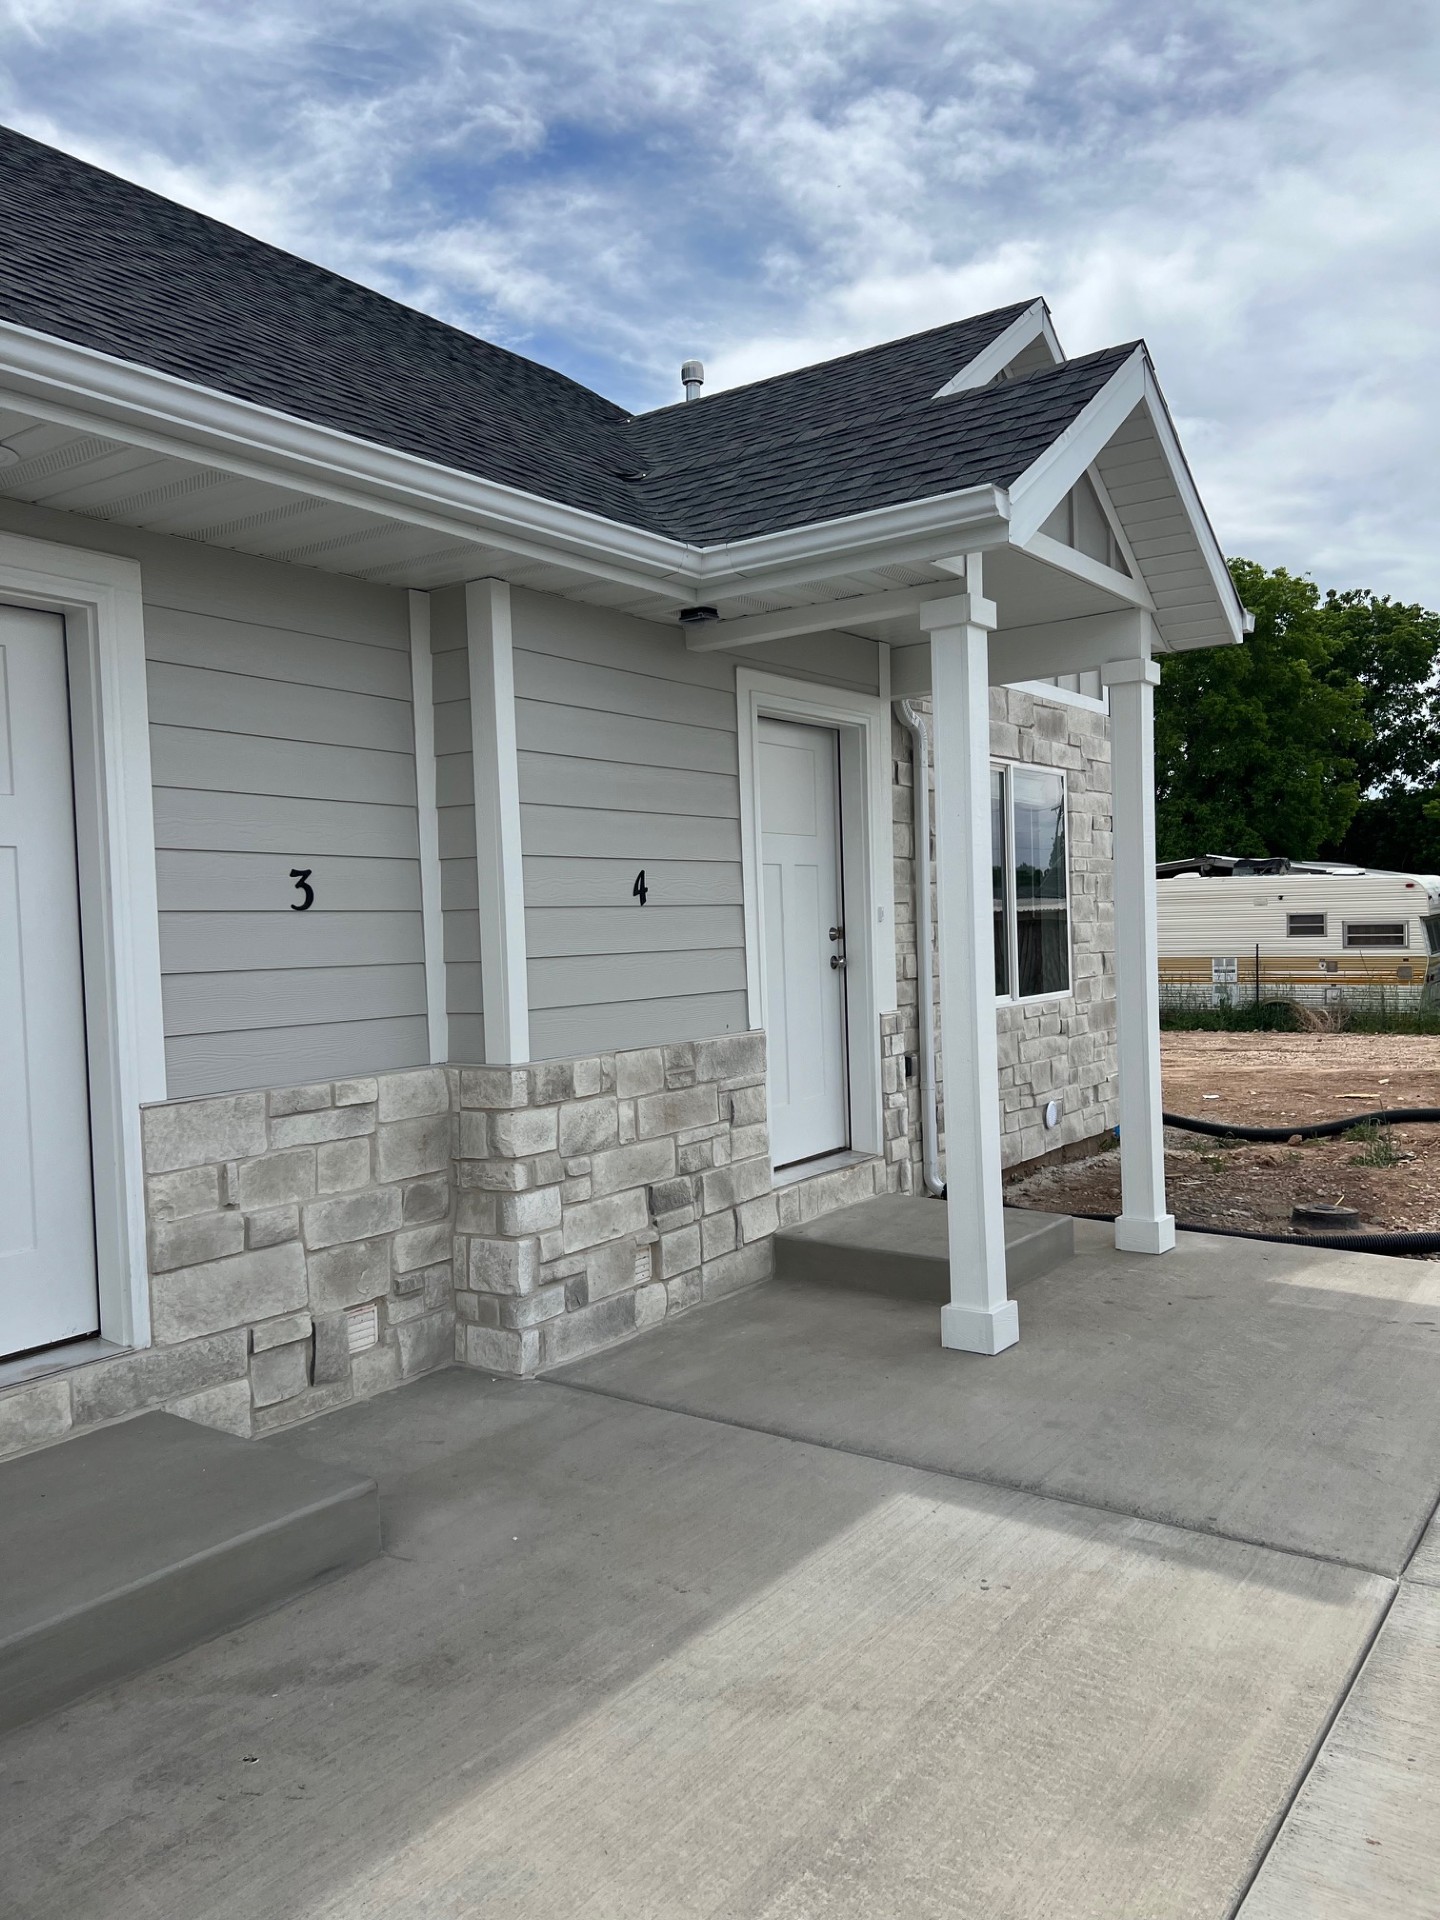
Much of what the townhome premium buys is everyday usefulness. But apartments here aren’t all hallway buildings: Priority Homes apartments have private exterior entrances.
| Factor | Loveless Estates townhome | Priority Homes apartment |
|---|---|---|
| Space | About 1,800 finished sq ft plus basement potential | Varies by bedroom count and unit |
| Levels | Multi-level, with stairs | Varies; may be easier single-level living |
| Neighbors | Shared side walls, none above or below | Depends on the building layout |
| Parking | Attached garage | Two dedicated spaces |
| Outdoors | Fenced backyard (on #53) | Varies by unit |
| Changes | More freedom, within HOA rules | Need management approval |
Owners handle the interior and anything the HOA doesn’t cover. Renters report problems and handle tenant duties, while management handles landlord repairs. Ask these on your tours.
Renting first can be a deliberate path to owning, not a setback. Six steps from lease to keys.
Choose a bedroom count and rent that leave room to save every month.
Emergency savings before down-payment savings, then money for closing and moving.
Pay on time, reduce costly debt and correct credit-report errors.
Learn the commute, schools, errands and seasons, and which part of town fits you.
A written lender quote, the exact home, taxes, insurance, HOA and inspection.
The home, payment, cash and timeline, not just because a lease is ending.
Renting usually needs far less upfront cash and has a more predictable monthly cost. Buying can build equity but adds loan costs, property tax, insurance, HOA dues, repairs, reserves and future selling costs. Compare an actual lease with a complete written purchase estimate.
In this guide the townhouse is bought and owned, while the apartment is rented under a lease. That changes the upfront cash, repairs, control, risk, possible equity and how you leave.
Published Priority Homes rents: Ray’s 2-bedroom $1,300 and 3-bedroom $1,450; Loveless 2-bedroom $1,550, 3-bedroom $1,750 and 4-bedroom $2,200. Call Chantel Bennett at (435) 660-1332 for availability.
Loveless Estates #53 at 233 W 815 N, shown at $389,900 on July 17, 2026 after a reduction from $399,900. Confirm the current price and status before comparing.
Usually. Loveless Estates homes are commonly described at about 1,800 finished square feet plus basement potential, with an attached garage and yard. Apartment size varies by unit.
No. Paying down the loan can build equity, but values can rise or fall, and repairs, HOA costs, loan costs, selling costs and a short ownership period can reduce or erase a gain.
Only after qualified tax advice. The rules depend on the loan, property, limits and whether you itemize, so not every homeowner gets an extra tax benefit.
There’s no universal cutoff. Model an early sale, your expected sale and a long hold with your actual loan and selling costs. A short or uncertain stay often favors renting.
Kerry Anderson at (435) 660-0264 for townhomes, Chantel Bennett at (435) 660-1332 for apartments, or the Priority Homes office at (435) 623-0897.
See a Loveless Estates townhome and a current Priority Homes apartment. Compare the real space, parking, privacy, repairs, monthly cost, upfront cash and your timeline before choosing.
Updated October 2026. Apartment rents from the current Priority Homes apartment pages; townhome example from the Loveless Estates #53 listing (July 17, 2026). Educational information only, not a loan offer, appraisal, or tax or legal advice.
A townhouse and an apartment can both provide a modern Nephi home, but they solve different problems. This guide compares the upfront cash, complete monthly cost, space, maintenance, privacy, pets, parking, equity potential, transaction risk, and timeline—without assuming that buying or renting always wins.
An apartment is usually the simpler short-term commitment. It requires less cash at move-in, transfers most building maintenance to management, and allows a household to leave at the end of the lease.
A townhouse can provide more control, space, privacy, garage and yard utility, and equity potential. It also exposes the owner to financing, closing costs, repairs, HOA obligations, market changes, and future selling costs. The winner is determined by your real numbers—not a universal five-year promise.
The financial and legal relationship matters more than the building label.
In this comparison, the townhouse buyer purchases a specific home, obtains title, finances or pays cash, carries owner insurance, pays property taxes and HOA dues, maintains the owner-responsible portions, and later controls the decision to sell. The apartment resident signs a lease, pays rent and required tenant charges, follows the lease and community rules, and returns possession when the tenancy ends.
| Decision factor | Townhouse owner | Apartment renter |
|---|---|---|
| Legal position | Owns the property interest defined by title and HOA documents | Receives the right to occupy under the lease |
| Upfront commitment | Down payment, closing costs, lender expenses, inspections, moving, and reserves | Application charges, deposit, first rent, pet charges, utility setup, and moving |
| Monthly payment | Mortgage if financed, taxes, insurance, HOA, utilities, maintenance, and reserves | Rent, renter’s insurance, utilities, pet rent, and any lease-authorized charges |
| Maintenance | Owner handles interiors and all items not assigned to the HOA | Manager or owner handles landlord obligations; renter handles tenant duties |
| Control | More freedom, subject to law, lender, structure, warranty, and HOA rules | Changes, pets, occupancy, and use are limited by the lease and policies |
| Exit | Must sell, retain, or legally rent the property; value and timing are uncertain | Can usually leave when the lease ends after satisfying notice and move-out terms |
| Financial outcome | May gain or lose equity depending on principal reduction, value, costs, and sale | No ownership equity, but retains capital not committed to the purchase |
A townhouse is not automatically legally owned “with the land,” and an apartment is not always a hallway-style building. Townhouse describes a physical housing form; apartment often describes a rental use. Title, plat, declaration, lease, and governing documents establish the legal rights and responsibilities.
Use real local options, but verify each one before making a comparison.
Ownership example · Loveless Estates
The featured live listing was shown at $389,900 on July 17, 2026. It reports three bedrooms and approximately 2,579 total square feet, with an attached garage, modern kitchen, multiple living areas, and a fenced backyard. Finished square footage and exact specifications must be confirmed.
Rental examples · Priority Homes Apartments
Published apartment pricing ranges from $1,300 to $2,200 per month. Ray’s offers 2- and 3-bedroom options. Loveless offers 2-, 3-, and 4-bedroom options. Availability and the actual lease control the decision.
| Current example | Published price | Bedroom count | Important verification |
|---|---|---|---|
| Ray’s Apartments | 2BR $1,300; 3BR $1,450 | 2–3 | Open unit, lease start, deposit, utilities, pets, parking, and exact condition |
| Loveless Apartments | 2BR $1,550; 3BR $1,750; 4BR $2,200 | 2–4 | Open unit, floor plan, lease, utilities, pets, parking, and actual finishes |
| Loveless Estates #53 | $389,900 purchase example | 3 | Live price, loan, completed area, HOA, taxes, insurance, incentives, and closing costs |
Buying usually requires much more cash before move-in, even when the monthly payment appears manageable.
A renter generally needs the move-in amounts required by the lease. A buyer must prepare for the down payment plus costs that do not become equity: lender and title charges, appraisal, inspections, prepaid taxes and insurance, moving, immediate purchases, and post-closing reserves. Seller or lender concessions may reduce some items, but they should be confirmed in writing rather than assumed.
| Upfront category | Townhouse purchase | Apartment lease |
|---|---|---|
| Primary payment | Down payment selected with the lender | First month’s rent or prorated rent |
| Transaction expenses | Loan, appraisal, title, settlement, recording, inspection, and prepaid costs | Application, screening, administrative, or lease charges where permitted |
| Deposit | Earnest money may be credited at closing; reserves remain important | Security deposit and any pet deposit or other lease-authorized deposit |
| Immediate purchases | Furniture, window coverings, tools, maintenance supplies, and any excluded appliances | Furniture, household items, and any renter-provided equipment |
| Recommended liquidity | Cash remaining after closing for repairs, deductibles, HOA issues, and personal emergencies | Emergency fund for rent, moving, vehicle, employment, and personal disruptions |
| Illustrative percentage | Down-payment amount | What this does not include |
|---|---|---|
| 3.5% | $13,646.50 | Eligibility, mortgage insurance, closing costs, reserves, and lender requirements |
| 5% | $19,495 | Closing costs, prepaid items, mortgage insurance, moving, and reserves |
| 10% | $38,990 | Closing costs, prepaid items, inspection, and reserves |
| 20% | $77,980 | Closing costs, prepaid items, inspection, moving, and reserves |
These percentages are math examples—not loan-program promises. Eligibility, minimum investment, mortgage insurance, rates, points, reserves, seller concessions, occupancy rules, and closing costs depend on the borrower, property, lender, and current program.
Mortgage principal and interest versus rent is not a complete comparison.
| Monthly item | Townhouse amount | Apartment amount | Evidence |
|---|---|---|---|
| Principal and interest / rent | $________ | $________ | Written lender quote or actual lease |
| Property tax | $________ | Included in landlord’s ownership cost | Current tax record and lender estimate |
| Owner or renter insurance | $________ | $________ | Property-specific and renter-policy quotes |
| HOA | $________ | Not separately paid unless the lease states otherwise | Current HOA statement and documents |
| Mortgage insurance | $________ | Not applicable | Lender quote |
| Utilities | $________ | $________ | Responsibility matrix and recent usage |
| Interior maintenance | $________ | Tenant duties only; landlord obligations per lease and law | Owner reserve or lease |
| Capital reserve | $________ | Not a renter ownership expense | Property age, systems, warranties, and reserve policy |
| Pet charges | HOA and owner costs as applicable | $________ | HOA rules or lease |
| Total monthly housing cost | $________ | $________ | Compare using the same month and household |
Principal is not a normal operating expense—but it is still cash leaving the household. A portion of a mortgage payment may reduce the loan balance and increase equity. That equity is not immediately spendable without a sale or additional borrowing, and it can be offset by falling value, transaction costs, or property expenses.
Ownership can build wealth, but the outcome should be modeled—not declared.
Townhouse ownership can create equity through loan principal reduction and changes in market value. The owner may also benefit from certain tax treatment if the current law and individual tax situation allow it. None of these outcomes should be treated as guaranteed monthly discounts.
More predictable component
An amortizing mortgage generally reduces the balance as scheduled payments are made. The exact first-year amount depends on the loan amount, rate, term, payment history, and loan structure.
Uncertain component
The property may rise, remain flat, or decline. A forecasted percentage should be shown as a scenario—not deducted from current housing cost as though already earned.
Tax-specific component
Mortgage-interest and other tax effects depend on law, itemization, debt limits, property use, and the taxpayer. Use a CPA or qualified adviser rather than a generic bracket assumption.
Do not publish “the owner is $47,000 ahead after five years” as a fact. That conclusion depends on appreciation, financing, repairs, HOA costs, tax treatment, opportunity cost, rent changes, selling expenses, and the exact sale date. Present a range of scenarios instead.
| Five-year item | Townhouse scenario | Apartment scenario |
|---|---|---|
| Total monthly housing payments | $________ | $________ |
| Upfront transaction and move-in costs | $________ | $________ |
| Maintenance, repairs, and reserves | $________ | Tenant-paid duties and damages: $________ |
| Principal reduction | $________ | $0 ownership equity |
| Estimated sale value | Downside / base / upside | Not applicable |
| Estimated selling and exit costs | $________ | Lease-end and moving costs: $________ |
| Investment return on uncommitted renter capital | Opportunity cost: $________ | Actual return if invested: $________ |
| Net five-year position | $________ | $________ |
The townhouse premium may purchase daily utility—not merely an ownership label.
| Lifestyle factor | Loveless Estates example | Priority Homes apartment | Verify |
|---|---|---|---|
| Square footage | 2,579 total square feet; finished and unfinished categories must be confirmed | Varies by bedroom count and exact unit | Measure usable rooms and compare finished-to-finished area |
| Levels | Multi-level living with stairs and basement potential | Layout varies; may provide easier single-level daily living | Accessibility, furniture, children, pets, and long-term mobility |
| Entry | Private front entrance | The supplied apartment image shows private exterior entries | Exact unit access, stairs, lighting, security, and deliveries |
| Shared walls | Attached-home walls; no unit above or below in the typical plan | Depends on apartment layout and building configuration | Visit during occupied hours and ask about noise policies |
| Garage and storage | Attached garage plus basement and interior storage potential | Published dedicated parking; storage varies | Vehicle dimensions, guest parking, trailers, and storage rules |
| Outdoor space | Featured listing includes a fenced backyard with grass and sprinklers | Private or common exterior areas vary by unit | Maintenance, pets, gates, irrigation, sun, and actual dimensions |
| Customization | Greater interior control, subject to structure, code, warranty, and HOA | Changes require lease and management approval | Painting, fixtures, shelving, television mounting, and exterior changes |
Use finished space correctly. Loveless Estates is commonly marketed with approximately 1,800 finished square feet plus basement potential. Many Santaquin-area townhomes are closer to roughly 1,500 finished square feet. Compare finished-to-finished first and then value the basement separately.
Renting transfers more responsibility; ownership provides more control and more exposure.
Townhouse ownership
The owner handles the interior and every item not assigned to the HOA. That may include appliances, plumbing within the unit, electrical components, flooring, paint, fixtures, HVAC responsibilities, deductibles, and damage. The current HOA documents control the exterior boundary.
The lease assigns tenant duties and explains how maintenance requests are submitted. Renters are still responsible for cleanliness, prompt reporting, ordinary care, damage caused by occupants or guests, utilities assigned by the lease, and access for lawful repairs.
Your expected length of stay can change the answer more than any single monthly figure.
Renting often fits when employment, family, location, income, school, or relationship plans may change soon. Model lease obligations and moving costs.
Compare both paths carefully. Buying may work, but purchase and selling costs can matter heavily if the home must be sold sooner than planned.
Ownership has more time to spread transaction costs and reduce principal, but the buyer must still afford repairs, HOA, insurance, and market fluctuations.
| Scenario | Reason | Inputs to model |
|---|---|---|
| Earlier-than-planned sale | Job, family, health, payment stress, or location change | Flat or lower value, full selling costs, repairs, concessions, and slower marketing |
| Expected sale | The household follows its current plan | Conservative value range, realistic selling cost, remaining loan, and maintenance |
| Long hold | The home remains useful for many years | Repairs, replacements, HOA changes, refinance risk, opportunity cost, and long-term fit |
There is no universal “five years minimum.” A longer stay generally improves the chance to spread transaction costs, but a favorable or unfavorable market can change the result. Use your actual loan and realistic exit assumptions.
A good apartment decision can be better than a premature purchase; a sound purchase can be better than indefinite renting.
Townhouse may fit when
Do not buy simply because “rent is throwing money away.” Renting purchases housing, maintenance allocation, and flexibility. Do not rent indefinitely merely because ownership feels complicated either. Compare the complete value each path provides during the period you realistically expect to use it.
Renting first can be a deliberate ownership strategy rather than a financial failure.
Phase 1
Select the bedroom count and rent that preserve monthly savings rather than stretching to the maximum available unit.
Create emergency savings before separating money for a down payment, closing, moving, and post-closing repairs.
Pay on time, reduce costly debt, avoid unnecessary new obligations, and correct credit-report errors.
Learn the commute, schools, healthcare, errands, seasons, neighborhood patterns, and which location fits.
Use a written lender quote, exact property, taxes, insurance, HOA, inspection, and comfortable reserve target.
Move when the home, payment, cash position, timeline, and ownership responsibilities all fit—not merely when a lease ends.
For a townhouse, bring your price range, financing status, move date, space requirements, and HOA questions. For an apartment, bring your bedroom count, move date, pet status, budget, and preferred community.
Balanced answers for renters and prospective buyers in Nephi.
For this guide, the townhouse is purchased and owned, while the apartment is occupied under a lease. That changes the upfront cash, maintenance, control, risk, potential equity, and exit process.
Renting generally needs less upfront cash and may have a lower predictable monthly cost. Buying can build equity but adds loan costs, taxes, insurance, HOA dues, maintenance, reserves, and future selling costs. Compare the actual lease with a complete written purchase estimate.
Published Priority Homes pricing ranges from $1,300 to $2,200 per month: Ray’s 2BR at $1,300 and 3BR at $1,450; Loveless 2BR at $1,550, 3BR at $1,750, and 4BR at $2,200. Call Chantel for current availability and lease terms.
The current Loveless Estates example is 233 W 815 N #53, MLS #2142576, shown at $389,900 on July 17, 2026. Confirm its live status and all specifications before using it in a financial comparison.
The featured listing reports 2,579 total square feet, but finished and unfinished space must be separated. Priority Homes commonly describes approximately 1,800 finished square feet plus basement potential. Apartment size varies by exact unit.
No. Principal reduction may build equity, but market value can rise or fall. Repairs, HOA costs, loan expenses, selling costs, and a short ownership period can reduce or eliminate a gain.
Only after qualified tax advice. The IRS rules depend on the debt, property, use, limits, and whether the taxpayer itemizes. Not every homeowner receives an incremental tax benefit.
There is no universal cutoff. Model an early sale, expected sale, and long hold using the actual loan, maintenance, value scenarios, and complete selling costs. A short or uncertain stay often favors renting.
Townhouse owners remain subject to HOA, insurance, local-law, and nuisance rules. Apartment residents follow the lease and pet policy. Priority Homes’ current apartment pages publish pet approval requirements and charges that should be confirmed before applying.
Call Kerry Anderson at (435) 660-0264 for townhouses. Call Chantel Bennett at (435) 660-1332 for apartment availability.
Loveless Estates townhouses · Loveless Apartments · Ray’s Apartments
Kerry Anderson — Equity Real Estate: townhouse inventory, tours, buyer representation, offers, and the purchase process. (435) 660-0264.
Chantel Bennett — Apartment Management: Loveless and Ray’s availability, applications, tours, and lease questions. (435) 660-1332.
Priority Homes Office: general company and housing questions. (435) 623-0897.
Tour a Loveless Estates townhouse and a current Priority Homes apartment. Then compare the real space, parking, privacy, maintenance, complete monthly cost, upfront cash, commute, and timeline before choosing.
Visit us at 1451 S Main, Nephi, call 435-623-0897, or send a message and we will get back to you.